The Complete Private Capital Advisory and Secondaries Guide
A complete guide to private capital advisory, the investment banking group that advises funds and their investors on secondaries, continuation vehicles, fundraising, GP stakes, and fund finance. Covers fund economics, LP-led and GP-led secondaries, the buyer universe, the latest market data, and the PCA interview.
A complete guide to private capital advisory, the investment banking group that advises funds and their investors on secondaries, continuation vehicles, fundraising, GP stakes, and fund finance. Covers fund economics, LP-led and GP-led secondaries, the buyer universe, the latest market data, and the PCA interview.
Understand what private capital advisory does, how it differs from sponsors coverage, and who the major franchises are
Master fund economics: the LPA, fees and carry, waterfalls, DPI and TVPI, and how NAV is set
Navigate LP-led secondaries from the portfolio sale process to pricing at a discount to NAV
Analyze GP-led secondaries and continuation vehicles, including LP elections, carry economics, and conflicts
Evaluate fundraising, GP stakes, NAV loans, and preferred equity as the wider private capital toolkit
Prepare for PCA interviews with the continuation vehicle and LP portfolio sale walkthroughs and the latest market data
The condensed track through this guide: a short sequence of focused reads, each with MCQ checkpoints to lock the concepts in, covering exactly what you need to be ready in the room.
Understanding The Complete Private Capital Advisory and Secondaries Guide: A Complete Overview
Private capital advisory is the investment banking group that advises private equity funds, the managers who run them, and the institutions that invest in them at the fund, manager, and LP levels, working with company-level specialists where needed. Where a financial sponsors banker helps Blackstone buy or sell a business, a private capital advisory (PCA) banker helps Blackstone sell a stake in a fund, move a prized company into a continuation vehicle, raise its next fund, or sell a piece of the management company itself. The clients are the same. The product, the counterparties, and the technical toolkit are entirely different, and the group has grown from a placement-agent sideline into one of the most active advisory businesses on the Street.
The engine behind that growth is the secondaries market, which gives investors and managers liquidity before the underlying companies are sold. In an LP-led sale, a limited partner sells its fund interests to a new investor; in a GP-led transaction, the manager runs the process itself, most often through a continuation vehicle. Both sides keep setting records: after a record 2025, about $226 billion of secondary volume in Evercore's count and $240 billion in Jefferies', the first half of 2026 was the strongest first half in both surveys, with GP-led deals just over half of volume. Behind those numbers sit limited partners waiting on distributions and a growing pool of buyer capital, and the advisor who runs the process between them is the PCA banker.
This guide covers the whole business from that advisor's seat: what PCA does and who the franchises are, the fund economics every process prices off, LP-led secondaries, GP-led secondaries and continuation vehicles, primary fundraising and placement, GP stakes and fund finance, the buyer universe and how it underwrites, the latest market data and the outlook, and how to recruit into and interview for the group. Sponsors coverage, the group that serves the same clients at the portfolio-company level, is explained in the financial sponsors group explainer.
What Private Capital Advisory Is and Who Does It
"Private capital advisory" is a label, not a standard org chart. Evercore, Lazard, Jefferies, and William Blair use the name; PJT runs the business as Park Hill, Houlihan Lokey and UBS as a Private Funds Group, and Campbell Lutyens, long the best-known independent, agreed in April 2026 to be acquired by Lazard. Some firms keep secondaries and primary fundraising in one team, while others split them: Evercore, for example, runs secondaries in its PCA group and primary placement in a separate Private Funds Group. Before an interview, find out which of these businesses the team you are meeting actually runs.
Four Related Business Lines
Four activities sit under the PCA umbrella. Secondaries advisory runs LP portfolio sales and GP-led processes. Primary placement, the oldest part of the business, helps a manager position and raise a fund. GP stakes advisory deals with ownership of the management company itself, while fund finance specialists arrange NAV loans, preferred equity, and other fund-level capital. The four share clients and relationships but not necessarily staff: at one firm a senior banker covers a sponsor across all of them, at another each line sits with a separate team. The Private Capital Toolkit explains how to tell the client, the mandate, and the team apart.
| Firm | Group name | Where it is strongest |
|---|---|---|
| Evercore | PCA and separate Private Funds Group | PCA secondaries; PFG primary advisory and placement |
| Lazard | Private Capital Advisory | Large LP portfolio sales, GP-leds |
| Jefferies | Private Capital Advisory | Large mandates, the most-cited market review |
| PJT Partners | Park Hill | Placement heritage, mid-market and single-asset GP-leds |
| Campbell Lutyens | Independent; Lazard acquisition agreed April 2026 | Secondaries and placement, deep specialization |
| Houlihan Lokey | Private Funds Group | Expanded with the Triago acquisition, mid-market |
| Mizuho (Greenhill) | Secondary Advisory | LP-led and GP-led secondaries |
| William Blair, UBS, Rothschild, Raymond James, Moelis | PCA / Private Funds | Mid-market, regional, and GP solutions |
How the Business Makes Money
PCA earns success fees on secondaries transactions, placement fees on capital raised, and advisory fees on GP stakes and structured deals. The distinctive feature is who pays: in a GP-led transaction the general partner hires the advisor, but the advisor's process is supposed to serve the existing fund and its LPs, which is why the 2023 ILPA guidance says the advisor should be selected to benefit the fund overall and the LPAC should review both the choice and the fee. Managing that conflict well is the core professional skill of the group.
Fund Economics: The Foundation Every Process Prices Off
A PCA banker lives inside the limited partnership agreement. LP fund-interest sales are commonly quoted as a percentage of net asset value, every continuation vehicle is structured around carried interest, and every fundraise is a negotiation over terms, so the fund model has to be second nature.
Fees, Carry, and the Waterfall
A buyout fund charges a management fee on committed capital during the investment period and typically on invested capital after it, and earns carried interest, usually 20% of profits above an 8% preferred return with a catch-up. Fee levels are falling: Preqin recorded a mean management fee of 1.61% for funds raised in 2025, the lowest on record, as managers discounted to get funds closed. The waterfall that pays the carry comes in two forms. A European, or whole-of-fund, waterfall returns all LP capital and the preferred return before the GP earns any carry. An American, or deal-by-deal, waterfall pays carry on each realized deal, protected by a clawback if later losses mean the GP was overpaid. The choice matters enormously in a secondary, because a continuation vehicle may crystallize carry, with treatment depending on the existing waterfall, LP elections and negotiated terms, and the guide gives it a full treatment in Management Fees, Carried Interest, and the Distribution Waterfall.
- Carried Interest
The general partner's contractual share of fund profits under the agreed waterfall. The hurdle, catch-up, timing, loss treatment and clawback determine when carry is payable. A distribution or CV transaction does not automatically produce the same carry outcome for every investor.
DPI, NAV, and the LP Cash Flow Problem
Limited partners judge a fund on four numbers: DPI (cash distributed divided by cash paid in), RVPI (remaining value divided by cash paid in), TVPI (the sum of the two), and IRR. In 2025 DPI became the number that mattered, because with holding periods averaging around seven years, distributions lagged and LPs could not fund new commitments from old ones. Net asset value is the GP's quarterly mark of what the remaining portfolio is worth, set under fair-value accounting and the fund's valuation policy, and it is a common pricing reference for LP fund-interest sales: a buyer bidding "90" is offering 90% of the NAV at an agreed reference date, adjusted for capital calls and distributions since. Understanding why buyers discount NAV, from valuation conservatism and unfunded commitments to the cost of capital, is the whole art of pricing, and it starts with How Fund NAV Is Set.
- Net Asset Value (NAV)
In private equity, the general partner's periodic valuation of a fund's remaining investments, net of fund-level liabilities, attributable to the limited partners. NAV is reported quarterly under fair-value accounting and serves as the reference price in the secondary market, where bids are quoted as a percentage of NAV at a specified reference date and then adjusted for interim cash flows.
The demand for liquidity comes from the LP side as much as the GP side. Overallocation is the mechanism: when public markets fall or private marks lag, an LP's private equity weighting rises above its target without any new investment, the denominator effect, and by 2025 more than half of surveyed pension funds were over target. That is why pensions and sovereign wealth funds supplied nearly half of LP portfolio sales in the first half of 2025, and why the group's whole client base is described in Why LPs and GPs Need Liquidity.
LP-Led Secondaries: Selling Fund Interests
The original product is the LP portfolio sale. A limited partner hands an advisor a list of fund interests, the advisor packages and markets them to secondary buyers, and the interests change hands at a price expressed as a percentage of NAV. The quoted percentage is a starting point: the purchase agreement determines the cash-flow adjustments and final settlement.
The Process and the Mosaic
The advisor's job runs from portfolio selection and the choice of a reference date through marketing, two rounds of bids, transfer approvals, and closing. The distinctive tool is the mosaic: instead of selling the whole portfolio to one buyer, the advisor lets different buyers take the funds they know best and stitches the winning bids together. A mosaic can lift the blended price, but every extra buyer adds consents, documentation, and the risk that some interests go unsold. Deferred payments raise the headline bid in a similar way, at the cost of later cash and exposure to the buyer's credit. The LP Portfolio Sale Process explains how an advisor weighs these choices.
Portfolio selection and reference date
The LP picks the interests to sell and the advisor fixes the NAV date every bid will reference.
Marketing and first-round bids
Buyers receive the teaser and data room and submit indicative pricing per fund, as a percentage of NAV.
Mosaic construction and second round
The advisor combines the best bids by fund, invites final bids, and negotiates deferrals and structure.
Transfer approvals and documentation
Check the LPA and obtain required consents, address any rights of first refusal, and agree admission and transfer documents.
Closing and true-up
Price is adjusted for capital calls and distributions since the reference date and the interests transfer.
Pricing by Strategy
Buyers quote a percentage of NAV, but the number reflects asset quality, how credible the marks are, remaining commitments, the expected timing of distributions, and the buyer's own return target. Strategy matters because it drives those inputs: in Jefferies' first-half 2026 review, buyout interests averaged about 91% of NAV, credit about 89%, and venture about 79%. The headline percentage is also not the cash the seller receives. Under a simple dollar-for-dollar convention, a 90% bid on a reference NAV of 100, with 5 of capital calls and 12 of distributions since the reference date, pays 83 at closing, and the buyer takes on the unfunded commitments as a separate obligation. Pricing LP Interests works through the example.
| Strategy | What buyers ask |
|---|---|
| Buyout | Are marks supportable, and when can exits deliver cash? |
| Credit | What cash yield, credit losses, leverage, and remaining duration are expected? |
| Infrastructure | How durable are cash flows, and what capex and regulatory risks remain? |
| Venture | How uncertain are valuations, future funding, and exit timing? |
GP-Led Secondaries and Continuation Vehicles
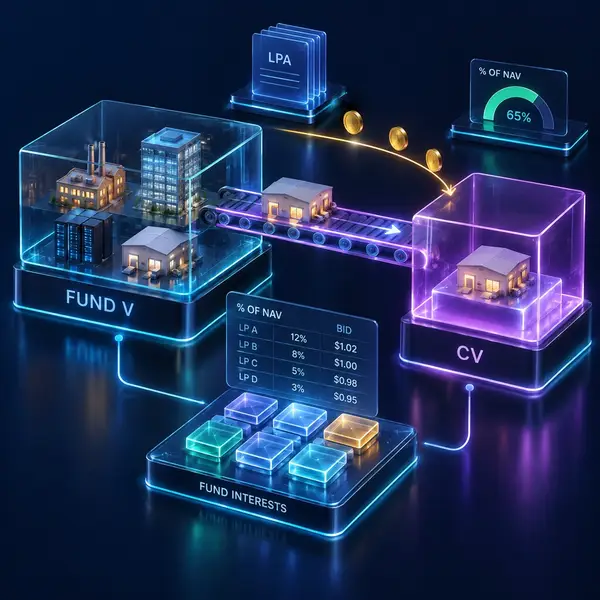
In a GP-led transaction, the manager initiates a process involving its funds or assets. A continuation vehicle acquires one or more investments from an existing fund under the same manager, usually with new capital and elections for existing investors. CVs are the largest part of GP-led activity but not all of it: tender offers and strip sales are GP-led too, which is why GP-led totals and CV totals should never be read as the same number.
Why Sponsors Do It
A continuation vehicle solves a timing problem. A sponsor may hold a company it believes has years of growth left, inside a fund approaching the end of its life. A CV lets investors who want cash sell at a price set through a buyer process, lets those who want to stay roll, and gives the sponsor more time with the asset. It is one option among several, alongside a third-party sale, a fund extension, a partial realization, or a recap, and the advisor has to judge price, risk, and alignment from the existing investors' side as well as the GP's. Single-asset CVs concentrate risk in one company and allow deep diligence; multi-asset CVs spread it across several, and neither structure automatically prices better. Continuation Vehicles Explained develops the comparison.
- Continuation Vehicle
A new vehicle that acquires one or more investments from an existing fund managed by the same GP. Existing investors may sell or roll on the terms offered. New capital can fund liquidity and further investment. The process requires careful treatment of valuation, conflicts, investor elections and manager economics.
The Process, the Elections, and the Economics
The advisor's role is to make a conflicted transaction defensible: benchmark value, run a buyer process to set the price, help select a lead investor who negotiates terms, and syndicate the rest. Existing LPs then elect to sell or roll, sometimes in part. Status quo terms describe a rollover that keeps an LP's existing economics as far as possible; they are a version of rolling, not a third option. The GP's side is the sensitive part: carry on the transferred assets may be crystallized, the GP usually reinvests alongside the new money, and fees and future capital needs are reset. CV Economics uses compact examples to show who funds the deal, who receives cash, and how each investor's outcome differs.
Continuation vehicles are no longer a buyout-only product. In Evercore's count, credit secondaries reached about $20 billion in 2025, close to double the prior year, with GP-led deals around 60% of that volume. Infrastructure secondaries were about $9.5 billion in Evercore's 2025 count and about $20 billion in Campbell Lutyens', a gap of definitions rather than markets, and venture GP-leds have arrived, with Insight Partners, General Catalyst, and NEA all running continuation funds on stakes in companies such as Databricks and Stripe. Tender offers, where a GP arranges a buyer for any LP who wants to sell at one price, and strip sales, where a fund sells a slice of every position, round out the GP-led toolkit.
Fundraising, GP Stakes, and Fund Finance
The other three business lines serve different needs: primaries help a manager raise capital, GP stakes change who owns the manager, and fund finance adds capital at the fund level. How much each matters, and which team runs it, varies by firm.
Placement and the 2025 Squeeze
A placement agent helps a GP raise a fund: positioning, the private placement memorandum and data room, LP targeting, the roadshow, terms and side letters, and the sequence of closes. PitchBook put the median time spent raising at about 12 months for US private equity funds that closed in 2025, down from nearly 17 in 2024, but 2025 was still the hardest year in some time: KPMG, using PitchBook data, put US private equity fundraising at a decade-low $278 billion, and Churchill Asset Management, also using PitchBook data, found that emerging managers raising their first to third fund launched more than 70% of new private equity funds but took only 11.6% of US capital raised, down from 18.6% in 2016. The money went to established managers with strong DPI, which is why placement agents increasingly package a secondary sale with a primary commitment, the stapled secondary. The growth market is private wealth: XA Investments counted 308 interval and tender offer funds with about $233 billion of net assets at the end of 2025, Jefferies estimated that evergreen vehicles took in about $113 billion in 2025 with roughly 41% allocated to secondaries, and a March 2026 Labor Department proposal, issued after an August 2025 executive order, would give 401(k) fiduciaries a safe harbor when selecting funds that hold private assets; its comment period closed in June 2026. The section on the private wealth channel explains the opportunities and constraints of reaching wealth investors.
GP Stakes
A GP stake is a minority interest, typically 10% to 35% and most often 20% to 25%, in the management company itself, giving the buyer negotiated rights to manager earnings and potentially carry or balance-sheet investments. Blue Owl (through the former Dyal business) focuses on large established managers, Goldman Sachs' Petershill business has invested in private markets managers since 2007, and Blackstone GP Stakes, Hunter Point, Investcorp, and Bonaccord (which raised $1.6 billion in January 2025 for mid-market managers) complete the dedicated buyer set. Valuing a GP is its own discipline, built on multiples of fee-related earnings with separate treatment of carry and the firm's own fund commitments, and it is covered in Valuing a GP.
NAV Loans and Structured Solutions
Fund finance is the fastest-growing corner of the toolkit. Subscription lines, secured on LP commitments, remain more than two-thirds of a fund finance market that passed $1 trillion. NAV loans, secured on the fund's portfolio, are the controversial growth product: the market is estimated at about $50 billion outstanding with 17Capital projecting $70 billion of deployment in 2025 and a path to $145 billion by 2030. Apollo's $5.4 billion facility for SoftBank's Vision Fund 2 is the largest on record, and Vista's $1.5 billion 2023 facility, part of which funded distributions, was the deal that triggered LP pushback and the ILPA's 2024 guidance asking for transparency and LP consultation when NAV loans fund distributions. Preferred equity from providers such as 17Capital and Dawson (formerly Whitehorse Liquidity Partners), and collateralized fund obligations that securitize fund portfolios into rated notes for insurers, complete the structured menu, and Liquidity Options Compared puts all of them side by side.
- NAV Loan
Financing whose repayment and borrowing capacity depend on a portfolio of investments rather than primarily on uncalled LP commitments. The borrower and security package vary, potentially including holding-company interests and distribution accounts. It can fund investment needs or LP distributions, but adds repayment obligations and does not convert borrowed cash into realized investment profit.
The Buyers and How They Underwrite
The buyer universe is the other half of every process. It includes dedicated secondaries funds such as Ardian, Lexington, Blackstone Strategic Partners, HarbourVest, and Coller, institutional buyers such as pensions and sovereigns buying directly, and a fast-growing group of evergreen vehicles raised from wealth clients. Their mandates, capital, liquidity needs, and concentration limits differ, so an advisor sizes up each buyer individually rather than reading capacity from a headline fundraise. Dry powder figures only compare cleanly on the same date and definition, and deployment, new fundraising, and leverage all change what a buyer can actually spend.
Assessing a Fund Interest and a CV
To read a bid, ask four questions: what the buyer expects to receive, what it must still fund, how long it must wait, and what could go wrong. Asset quality, NAV credibility, remaining commitments, and the risk of delayed exits all move the price a buyer can justify. A CV is closer to a direct investment: the buyer takes a fresh view of the company, the entry valuation, leverage, GP alignment, and the exit path. How Buyers Assess a Fund Interest and How Buyers Assess a CV explain these decisions through short examples.
Secondaries also have a distinctive return profile. Buying mature assets at a negotiated price can mitigate the J-curve, because the buyer skips the early years of fees and unrealized investments. But a discount to reported NAV is not a guaranteed day-one gain: the marks may be stale, any write-up depends on the fair-value evidence, and a CV that needs more capital may distribute little for years. The return that counts is realized cash, not the accounting mark at purchase.
Where the Market Stands and Where It Is Heading
Secondaries have set records in consecutive periods, and the advisory reviews that measure them each count differently. The market intelligence section follows the latest reviews survey by survey; the shape of the market is summarized here.
A Record Run, Measured Several Ways
Each review is best quoted on its own terms. Evercore's first-half 2026 review counted about $121 billion of volume, the strongest first half on record, with GP-led deals at 54% and single-asset continuation vehicles up 88% on a year earlier; Jefferies' July 2026 review counted about $118 billion, its first GP-led majority since 2021, with average LP portfolio pricing steady at 87% of NAV. The run builds on a record 2025, when Evercore counted about $226 billion and Jefferies about $240 billion; neither GP-led total is a CV-only number, since preferred equity and tender offers sit inside it.
What Advisors Expect Next
The outlook turns on four forces: whether distributions recover enough to ease the pressure on LPs, how much buyer capital secondaries funds and evergreen vehicles keep raising, the pace of primary fundraising, and the bid-ask spread between sellers anchored to NAV and buyers anchored to their return targets. Advisors' mid-2026 reviews expect another record full year, and Lazard's interim report projects about $305 billion for 2027; those are forecasts, and the secondaries market outlook sets out what each assumes and which drivers could break it.
Becoming a Private Capital Advisory Banker
The day-to-day work mixes transaction materials, investor communication, pricing comparisons, diligence, and financial analysis, and the balance depends on the team. A single-asset CV mandate can involve as much company-level work as an M&A deal, while an LP portfolio sale centers on fund interests, pricing grids, and transfer execution. Hours follow the live mandate calendar, and the group works closer to limited partners than most seats in banking.
Exits and the Interview
PCA experience leads naturally to the buy side of the same market, secondaries funds and fund-of-funds, as well as GP stakes investors, investor relations and capital formation roles at sponsors, and other advisory groups. The interview depends on the team. LP-led desks probe fund interests and pricing, CV teams test company risk and transaction economics much like an M&A interview, and primary teams focus on manager diligence and fundraising. Standard accounting and valuation questions still apply everywhere, and the careers section adds the two walkthroughs worth rehearsing: walk me through a continuation vehicle and walk me through an LP portfolio sale with the discount-to-NAV math.
Who This Guide Is For and How to Use It
The guide is written for three readers. Candidates recruiting for a private capital advisory or secondaries advisory team at Evercore, Lazard, Jefferies, PJT Park Hill, Campbell Lutyens, Houlihan Lokey, or any of the other franchises should read it as a course, from the landscape and fund economics through LP-led and GP-led secondaries to the careers section. Bankers in financial sponsors coverage or M&A who find a continuation vehicle competing with their sale process can use it as a reference on the product they are up against. And anyone interviewing with a secondaries fund, a fund-of-funds, or a placement team will find the buyer underwriting and fundraising sections explain the other side of the table.
Every article is written from the seat of the advisor running the process for a GP or an LP. Secondary buyers, fund counsel, administrators, and limited partners appear as clients and counterparties, never as the subject, and the guide assumes the reader already knows general valuation and LBO concepts. Explanations use prose, small tables and short calculations to make transaction choices clear. Where the underlying mechanics live elsewhere on the site, the guide links out: portfolio-company deals and sponsor exits to the Financial Sponsors Group guide, LBO modeling to the valuation guide, and direct lending to the DCM guide. Read together, the two sponsor guides cover both layers of the most valuable client relationship in investment banking.