Everything you need to ace your
investment banking interviews
1,000+ technical and behavioral questions with model answers, plus interview-ready sector and product guides. Land your dream offer.
Trusted by 5,000+ students applying at...


Explore IB IQ resources
Practice Online
Free to Start1,900+ technical and behavioral questions with model answers, interview-ready guides, brainteasers, and progress tracking, right in your browser.
Start practicing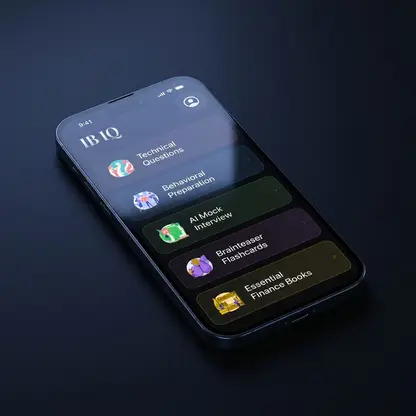
IB IQ App
iOS App1,000+ technical and behavioral questions with AI mock interviews that evaluate your answers and track your progress.
Explore the app
Free PDF Guide
Free PDF160+ pages of technical questions, valuation walkthroughs, behavioral frameworks, and model answer breakdowns.
Download for free
In-Depth Guides
1,000+ ArticlesComprehensive guides covering sector-specific prep (Healthcare, TMT, FIG), group coverage (ECM, DCM), and specialized career paths.
Explore the guides
The Blog
100+ PostsTechnical deep dives, recruiting timelines, networking strategies, and career transition playbooks written for serious candidates.
Browse articles
Deal Case Studies
NewLandmark deals reconstructed: the LBOs, mega-mergers, rescues, and collapses that shaped modern finance, with the numbers behind them.
Read the dealsTrusted by Students Worldwide
Join thousands of successful candidates preparing for investment banking careers
Active Users
Students preparing for interviews
Questions
Technical & behavioral
App Rating
Based on user reviews
Everything you need to ace your interviews
Comprehensive preparation tools designed by professionals who've been through the process
AI Mock Interviews
Practice with intelligent feedback and realistic interview scenarios
1,000+ Questions
Comprehensive question bank covering M&A, LBO, and technical topics
Behavioral Prep
Master fit questions with proven frameworks and templates
Detailed Solutions
Step-by-step explanations for every technical and case question
Progress Tracking
Monitor improvement with analytics and weak spot identification
Expert Content
Checked and validated by analysts from top investment banks
Practice with Intelligent Feedback
Our AI interviewer simulates real investment banking interviews, providing instant feedback on your technical knowledge and communication skills.
Realistic interview scenarios
M&A, LBO, and valuation questions in interview format
Personalized feedback
Detailed analysis of your responses and improvement areas
Progress tracking
Monitor improvement and identify knowledge gaps
AI Interviewer
Investment Banking Interview
"Walk me through a DCF model and explain the key assumptions."
"A DCF model projects future cash flows and discounts them to present value using WACC..."
Score: 8/10
Pass
Strong technical foundation
Great start! Consider explaining terminal value calculation next.
Why Investment Banking Interview Prep Matters
The Challenge
Investment banking interviews are among the most demanding in finance. Candidates face rigorous technical questions on valuation, M&A, LBO modeling, and accounting, alongside behavioral questions that assess communication and cultural fit. Top banks receive thousands of applications for a handful of positions.
The Solution
IB IQ helps candidates prepare smarter with a comprehensive question bank and AI-powered mock interviews that provide instant feedback. Instead of memorizing generic responses, you practice explaining concepts in your own words. Progress tracking identifies weak areas, and our curated reading list builds deeper knowledge.
The Result
Whether you are a student targeting summer analyst roles, a career switcher, or preparing for lateral moves, structured preparation dramatically improves your odds. The candidates who succeed are not necessarily the smartest, but the ones who practiced until their answers became automatic and confident under pressure.
Complete IB Interview Preparation Guide
Essential strategies and insights compiled by professionals who secured offers at Goldman Sachs, Morgan Stanley, and Blackstone.
Join 10,000+ students who have downloaded this resource
How to Prepare for Investment Banking Interviews
Investment banking interviews test a combination of technical knowledge, industry awareness, and personal fit. The process typically takes three to six months of focused preparation, and the candidates who start early and stay consistent tend to outperform those who cram in the final weeks.
What to Expect
IB interviews fall into two categories: technical questions that test your finance and accounting knowledge, and behavioral questions that assess whether you'd be a good fit for the team and the demanding hours of the job. Most candidates spend too much time on one category and not enough on the other.
Your preparation timeline depends heavily on your background. Finance majors from target schools may need less time on technical fundamentals but should still practice delivering clear, concise answers under pressure. Students from non-target schools typically need to invest more time building their network and filling knowledge gaps, but they're at no disadvantage if they start early enough.
A Structured Preparation Timeline
Months 1-2: Build your foundation. Study accounting, valuation, and M&A concepts. Read the key books. Start reaching out to bankers for informational interviews and networking calls.
Months 2-4: Move into active practice. Run through technical questions repeatedly until your answers feel natural. Work through behavioral questions using the STAR framework. Attend recruiting events.
Months 4-6: Refine and test. Do mock interviews with peers, mentors, or AI tools. Focus on your weak areas. Stay current on recruiting timelines so you don't miss application deadlines.
The biggest mistake candidates make is treating preparation as a knowledge exercise. You can know every concept perfectly and still bomb the interview if you can't communicate your answers clearly in 60 seconds or less. Practice out loud, not just in your head.
Technical Interview Questions
Technical questions are the backbone of investment banking interviews. Interviewers use them to gauge whether you actually understand finance or just memorized a study guide. The core areas include valuation methodologies, M&A concepts, leveraged buyouts, and accounting fundamentals.
Valuation
Valuation is where most interviews start. You need to be comfortable with the three main approaches: comparable company analysis (trading comps), precedent transactions, and discounted cash flow (DCF) analysis. Interviewers expect you to explain each method, when to use it, and the key assumptions that drive the output.
M&A and Deal Mechanics
M&A questions test your understanding of why companies merge and how deals work. Interviewers want to know that you understand concepts like accretion and dilution, synergies (both revenue and cost), and the differences between stock and cash deals. You should also be able to articulate what makes a company an attractive acquisition target.
Leveraged Buyouts
LBO questions come up frequently, especially at banks with strong sponsor coverage groups. At a minimum, you should be able to explain the mechanics of an LBO and walk through what makes a company a good candidate: stable cash flows, low capital expenditures, room to cut costs, and assets that can support leverage.
A DCF values a business on the cash it is expected to generate, discounted back to today. Project unlevered free cash flow for five to ten years: forecast revenue and margins down to EBIT, tax that EBIT, add back D&A, then subtract capex and the increase in net working capital. Then estimate a terminal value for everything beyond the forecast. Under the perpetual-growth approach, terminal value at the end of the forecast period equals the following year's unlevered free cash flow divided by (WACC minus g), where g must sit below WACC and stay consistent with the currency, the inflation assumptions, and sustainable long-run economic growth. Under the exit-multiple approach, apply a multiple such as EV/EBITDA taken from comparable companies to the final-year metric. Discount the cash flows and the terminal value at WACC, the blended cost of debt and equity. The sum is enterprise value; subtract net debt, preferred stock, and minority interest, then divide by diluted shares to reach an implied share price.
Two qualifications separate a strong answer from a memorized one. Unlevered cash flow pairs with WACC (levered cash flow pairs with cost of equity), and terminal value usually accounts for well over half of the total, so a careful analyst cross-checks the implied exit multiple or implied growth rate and presents a sensitivity table rather than a single point estimate.
Because a multiple prices the future, and identical current financials can conceal very different future economics. Two companies with the same revenue and EBITDA today can carry different growth expectations, but growth earns a higher multiple only when the company can reinvest at returns above its cost of capital; fast growth that demands heavy reinvestment at low returns adds little value. Risk matters as much as growth: cyclical demand, customer concentration, heavy leverage, or exposure to a fragile jurisdiction all earn a discount, while durable margins and high returns on invested capital earn a premium.
Market factors explain the rest. Thin trading liquidity, a small free float, the sector the market groups a company with, and takeover speculation all move multiples without any change in the reported numbers. In an interview, lead with growth quality, returns on capital, and risk, then show you understand these market drivers.
Mechanically, nothing changes. Ignoring taxes, transaction costs, and any market repricing, a company that raises $100 of debt and uses it to repurchase $100 of stock swaps one claim for another: equity value falls by $100 and net debt rises by $100, so enterprise value, the value of the operating business to all capital providers, is unchanged.
The second-order effects are where you show depth. EPS can rise or fall: it rises only if the reduction in shares outstanding outweighs the drop in net income from the new after-tax interest expense, so the outcome depends on the earnings yield of the repurchased shares versus the after-tax cost of the debt. Economic value can shift too: the interest tax shield adds value, while higher leverage raises expected distress costs and the risk carried by the remaining shareholders. And if investors read the buyback as a signal and the share price moves, measured market enterprise value moves with it.
An acquisition is dilutive when pro forma EPS for a period comes in below the acquirer's standalone EPS for that same period, which happens when the cost of the capital used to buy the target exceeds the earnings the target brings in. Think of it as a yield comparison. Each funding source has an after-tax cost in EPS terms: for new shares it is the acquirer's earnings yield (the inverse of its P/E), which is an accounting shortcut for the dilution from issuing stock and not the same thing as its economic cost of equity; for new debt it is the after-tax interest rate; and for cash it is the after-tax interest income given up. Compare that blended cost with the target's earnings yield on the equity purchase price, meaning target net income divided by the price paid for its shares including the premium, not its enterprise value. If the cost of funding is higher, the deal dilutes EPS before synergies.
The familiar shortcut follows from this: in an all-stock deal with no synergies, a buyer whose P/E is higher than the P/E implied by the offer price for the target is accretive, and the reverse is dilutive. That is a simplifying rule of thumb, not a merger model; a full analysis adds synergies, financing costs, transaction fees, and purchase accounting adjustments. Expensive debt or a rich premium can turn an otherwise accretive deal dilutive, and cost synergies can rescue one. Close by noting that dilution is not the same as value destruction: a deal can be dilutive in year one and still create value if growth and synergies arrive later.
Behavioral Interview Questions
Technical skills get you to the interview. Behavioral answers determine whether you get the offer. Bankers work 80 to 100 hours a week in small teams, and they want to know you're someone they can work alongside at 2 AM on a Saturday when a live deal is closing.
The Big Three Questions
Three questions appear in virtually every IB interview. "Tell me about yourself" is a 90-second pitch that connects the dots between your background, your interest in finance, and why you're in that chair today. Start with a brief personal hook, walk through your key experiences, and end with why investment banking is the logical next step.
"Why investment banking?" requires specificity. Reference a particular deal that fascinated you, a conversation with a banker that clarified what the job involves, or a class that made you realize you enjoy breaking down businesses analytically. Generic answers about "learning a lot" won't set you apart.
"Walk me through your resume" is similar but more detailed. The interviewer wants you to explain each major experience and why you made each transition. Every line on your resume should connect logically to the next, building a narrative that makes investment banking feel like the inevitable conclusion.
Situational and Fit Questions
Beyond the big three, interviewers test your self-awareness and interpersonal skills through situational questions. These require real examples from your experience, not hypotheticals. The STAR framework (Situation, Task, Action, Result) gives your answers structure, but the best responses feel conversational rather than formulaic.
Interviewers ask this because banking is teamwork under pressure, and they want evidence of what you specifically contributed to a group outcome. A project that went well can work if your role was meaningful; an example with a real obstacle, such as a member who stopped delivering or a disagreement over the approach, simply gives you more to show. Either way, the interviewer is listening for your judgment and your actions, not the group's.
Structure the answer with STAR (Situation, Task, Action, Result), spend most of your time on the Action step, and use "I" statements. Set the scene in two sentences, state your role, then describe what you did: how you divided the work, how you handled disagreement, what you adjusted when the plan changed. Close with a concrete result and one sentence on what you learned. Aim for about 90 seconds, and keep a second example ready because interviewers often follow up with "what would you do differently?"
The question tests self-awareness and coachability, not whether you have flaws. Choose an honest, bounded development area you have genuinely worked on: over-explaining when a busy reader wants the conclusion first, discomfort with public speaking, or a habit of working alone too long before asking for input. Be thoughtful about anything that reads as a core requirement of the analyst role, such as attention to detail or handling long hours; if a real weakness touches that territory, describe it precisely and show the progress you have made rather than dodging it. Skip humble brags like "I'm a perfectionist," which interviewers hear constantly and discount.
Structure the answer in three parts: state the weakness plainly in one sentence, describe the concrete corrective actions you took (feedback you sought, a system you built, deliberate practice), and give evidence of improvement, ideally something another person observed, such as a manager's review. Keep the same weakness across interviewers at a firm, because Superday panels compare notes.
This question tests whether you researched this firm or are recycling one answer across every bank. Build the response around two or three specific reasons, each backed by evidence from a different category: a deal you can discuss for 30 seconds beyond the headline and why its structure or sector interested you, a conversation with a current analyst or associate and something concrete they told you about staffing or culture, and the firm's positioning (a global platform, a pure advisory model, a middle-market focus) and why that fits what you want to learn.
Avoid generic praise like "top firm" or "great culture," which signals no research. Tailor the emphasis to the type of bank: cross-border reach and product breadth at a bulge bracket, senior exposure and conflict-free advice at an elite boutique. Keep it to 60 to 90 seconds and connect the reasons to your broader story, so it reads as a considered choice rather than flattery.
Interviewers use this to predict how you will handle setbacks in banking: a deal that collapses, a model an MD tears apart at midnight. They are listening for ownership, learning, and credible evidence that your behavior changed. Choose a genuine professional or academic failure with real stakes, such as a team project where you did not check in until it was too late or a deliverable built on assumptions nobody had reviewed. Avoid anything involving ethics or interpersonal conflict that reflects badly on you, and avoid trivia like oversleeping. Enough distance to show the change stuck helps, but there is no fixed rule about how old the story must be.
Keep the failure and its consequences brief, take responsibility without blaming others, then spend most of the answer on what you changed: the exact habit you adopted, such as sharing drafts early or scheduling regular check-ins. The strongest answers add a short follow-up example where that new habit produced a better outcome.
The Investment Banking Interview Process
The IB recruiting process has its own rhythm, and understanding the timeline gives you a significant advantage. Whether you're recruiting on-cycle as a junior in college or pursuing off-cycle opportunities, the stages follow a fairly predictable pattern.
Networking and Applications
Networking begins 6-12 months before interviews, long before any formal applications open. For most candidates, especially those from non-target schools, networking is what gets your resume past the initial screen. Reach out to alumni at target banks, attend firm-sponsored events, and request informational interviews. The goal isn't to ask for a job directly; it's to build genuine relationships with people who can advocate for you internally.
Once applications open, your resume needs to be polished and tailored to banking. Banks receive thousands of applications, and many are filtered by GPA cutoffs before a human ever sees them. Your resume should clearly highlight relevant experience, quantified achievements, and any finance-related coursework.
First Rounds and Superdays
First-round interviews are typically 30-minute phone or video screens conducted by analysts or associates. Expect a mix of behavioral questions ("Tell me about yourself," "Why IB?") and basic technical questions ("Walk me through the three financial statements," "What's the difference between enterprise value and equity value?"). The bar here is competence: interviewers are checking that your technical knowledge is solid enough to justify bringing you on-site.
Superdays are a full day (or half day) of back-to-back interviews at the bank's office. You'll typically meet four to six interviewers, ranging from associates to managing directors. The questions get harder and more conversational. Senior bankers tend to focus on your fit, your story, and your ability to think on your feet. Junior interviewers drill deeper on technicals. Stamina matters; your energy and enthusiasm need to stay consistent from interview one to interview six.
Offers and Decisions
Offers typically come within days of the Superday, sometimes the same evening. If you receive an offer, you'll usually have a limited window to accept. If you're managing multiple processes, communicate transparently with recruiters. Banking is a small world, and how you handle the offer process matters for your reputation.
Common Mistakes and How to Avoid Them
After reviewing thousands of candidate experiences, certain patterns emerge. The most common interview mistakes aren't about getting a technical question wrong; they're about preparation gaps and poor self-awareness.
Preparation Gaps
Not practicing answers out loud. Reading a study guide is not the same as explaining a concept to another person. The gap between understanding a DCF in your head and articulating it clearly in 60 seconds is enormous. Practice with a friend, a mentor, or an AI mock interview tool. Record yourself and listen back. You'll notice filler words, rambling, and unclear transitions that you'd never catch otherwise.
Underestimating behavioral preparation. Technical candidates often assume their finance knowledge will carry them. But banks routinely reject technically strong candidates who give flat, uninspiring behavioral answers. Your story needs to be tight, authentic, and practiced enough that it sounds natural without sounding memorized. Spend at least a third of your prep time on behavioral questions.
Not staying current on markets. You should be able to discuss at least two or three recent deals or market developments. If an interviewer asks "What's happening in markets?" and you go blank, it signals that you don't actually follow finance outside of interview prep. Read the Financial Times, Wall Street Journal, or Bloomberg for 15 minutes a day. It compounds quickly.
Networking Pitfalls
Treating networking as transactional. Sending a cold email asking for a referral is not networking. Building a relationship over multiple touchpoints and genuinely learning about someone's experience is. The candidates who get internal referrals are the ones who showed up to coffee chats with thoughtful questions and followed up with a thank-you note, not the ones who asked "Can you refer me?" in their first message.
Interview Day Errors
Giving generic answers to "Why IB?" and "Why this bank?" If your answer could apply to any bank or any industry, it's not specific enough. Interviewers can tell when you've done real research versus when you're recycling a template. Mention a specific deal, a specific person you spoke with, or a specific aspect of the group's culture that resonates with you.
Ignoring the questions you ask them. The final five minutes of every interview are reserved for your questions. Asking nothing, or asking something you could have Googled, signals low interest. Prepare thoughtful questions that show genuine curiosity about the team's deal flow, the group's culture, or what the interviewer personally enjoys about the job.
From the Blog
Guides and strategies to help you prepare for investment banking interviews
How to Answer "Walk Me Through a DCF" in IB Interviews
Master the most common valuation interview question. Learn the exact framework to walk through a DCF model clearly and confidently, including formulas, common follow-ups, and what interviewers really want to hear.
Read more →
Mastering the "Walk Me Through Your Resume" Question
Learn how to craft a compelling, structured response to the classic investment banking interview question: "Walk me through your resume."
Read more →
Breaking into IB from a Non-Target School: Realistic Strategy
Comprehensive guide for non-target students pursuing investment banking careers. Learn proven strategies for networking, resume building, and alternative pathways that actually work.
Read more →