Introduction
An analyst's first live deal usually arrives with a code name, a short list of people allowed to know about it and an email from compliance. From that moment the analyst holds material non-public information, or MNPI: facts about a client or a transaction that could move a stock if the market knew them. Handling it correctly is the first professional obligation of the job, and the one with the most permanent consequences when it goes wrong.
Banks organize themselves around that obligation. They split staff into a private side and a public side, separate the two with information barriers, track sensitive companies on watch and restricted lists, and police employees' personal accounts. Most of this arrives as a few compliance modules during training, squeezed between the accounting refresher and the modeling tests, which is why new hires tend to underestimate it.
This post explains what makes information material and non-public, how the walls and lists work, how wall-crossing shares deal information on purpose, what personal trading rules look like, and what happened to bankers who broke them. It describes how the system generally works; it is not legal advice, and your firm's policies and compliance team are always the final word.
What Makes Information Material and Non-Public
US insider trading law rests mostly on Section 10(b) of the Securities Exchange Act and the SEC's Rule 10b-5, which prohibit fraud in connection with buying or selling securities. Courts read them to bar trading on MNPI in breach of a duty of trust or confidence, and to bar passing it to someone who trades. Two words in the acronym carry most of the weight.
Materiality: Would a Reasonable Investor Care?
Information is material when there is a substantial likelihood that a reasonable investor would consider it important in deciding whether to buy or sell. The Supreme Court set that standard in TSC Industries v. Northway (1976) and applied it to Rule 10b-5 in Basic v. Levinson (1988), a case about merger talks. The Court refused a rule under which negotiations become material only once price and structure are agreed: for a contingent event, materiality depends on the probability that it happens and its magnitude if it does.
A takeover is enormous for the target's shareholders, so even early talks can be material. The categories a junior banker handles most often:
- Unannounced mergers, acquisitions, tender offers and sale processes, including who the bidders are
- Planned stock or bond offerings and block trades, with their size and timing
- Projections, results and guidance shared before public release
- Financing terms, restructuring talks and management changes
When Information Becomes Public
Information stays non-public until it has been disseminated in a way that reaches investors broadly, such as a press release, an SEC filing or a public announcement, and the market has had time to absorb it. A rumor does not make your knowledge public: if a news story speculates about a sale and you know it is true, your confirmation is itself MNPI.
You also do not need to work for the company to be bound. Under the misappropriation theory, upheld by the Supreme Court in United States v. O'Hagan (1997), trading on confidential information in breach of a duty owed to its source is fraud. O'Hagan was a partner at a law firm representing a bidder for Pillsbury who bought Pillsbury options; a banker advising an acquirer stands in the same position toward the target's stock.
- Material Non-Public Information (MNPI)
Information about a company or its securities that a reasonable investor would consider important to an investment decision and that has not been disseminated to the public. In investment banking, MNPI includes unannounced deals, offerings, projections and financing plans. Trading on it, or passing it to someone who trades, can violate US securities law.
Private Side vs Public Side of a Bank
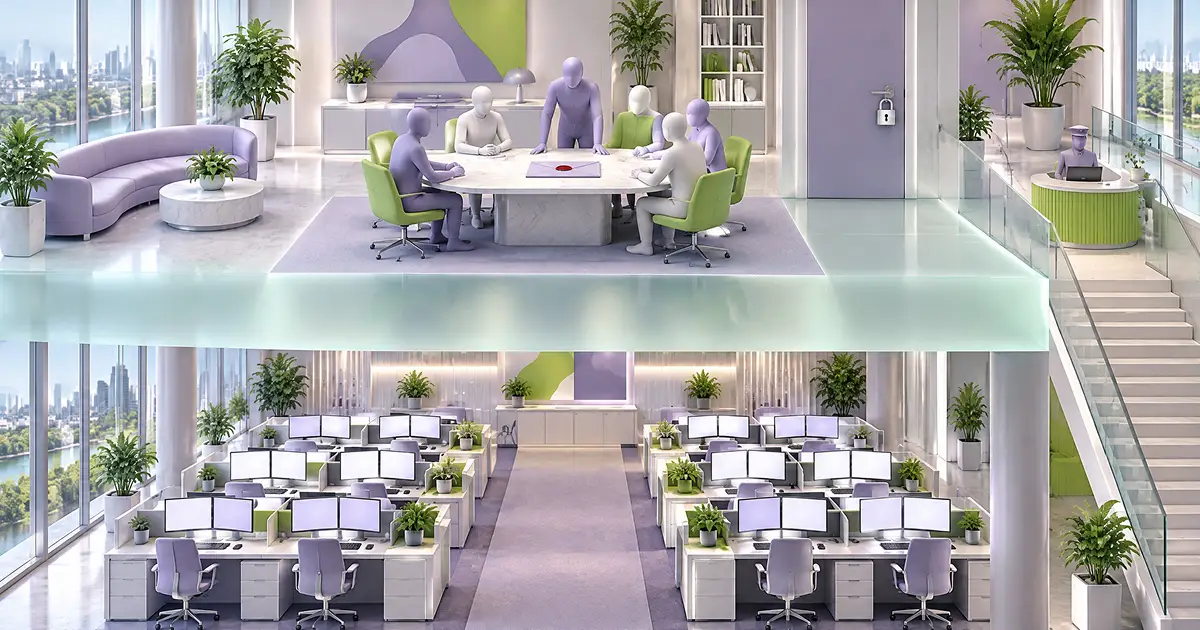
A bank that advises companies and also trades their securities has a built-in conflict. The private side receives confidential client information as part of its work; the public side trades, sells and publishes research using public information only.
| Feature | Private side | Public side |
|---|---|---|
| Typical groups | Coverage, M&A, capital markets origination | Sales, trading, equity research |
| Information held | Client MNPI as a matter of course | Public information only |
| Talks to investors | Not about client deals | Constantly |
| How MNPI crosses | Only with compliance approval | Wall-crossing, chaperoned calls |
| Main risk | Leaking or trading on deal information | Receiving MNPI it should not have |
Where Analysts Sit
An investment banking analyst is a private-side employee from day one. Some roles sit closer to the line: the equity syndicate desk connects ECM bankers with the trading floor during live offerings, and research analysts work under separate FINRA rules that limit their contact with bankers. Our ECM guide maps how the wall separates ECM bankers from the equity trading floor desk by desk. For an analyst in M&A or a coverage group the point is simpler: you are inside, and almost everyone beyond your deal team is outside.
Why the Law Requires a Wall
Information barriers are not just good practice. Section 15(g) of the Exchange Act requires every registered broker-dealer to establish, maintain and enforce written policies and procedures reasonably designed to prevent the misuse of MNPI by the firm or anyone associated with it. That statute is the source of the policies new hires sign, and it means a firm whose barriers fail can be charged itself, separately from any employee who traded.
- Information Barrier (Chinese Wall)
A set of policies, physical separations and system controls that stops material non-public information held by one part of a firm from reaching people who could trade on it or share it. Also called a Chinese wall or ethical wall, it is what allows a bank to advise companies and trade their securities at the same time.
Banks build the barrier in layers: separate floors and badge access, deal folders open only to named team members, recorded lines and surveillance of email and chat.
Wall-Crossing: Sharing Deal Information on Purpose
Sometimes a deal needs outside input before it is public. A company planning an offering wants to know whether investors will buy it; a selling shareholder wants banks to bid for a block of its stock. The answer is a wall-crossing, a controlled process in which an outside investor, or a public-side colleague, agrees to receive MNPI and to stop trading the affected stock.
The bank first approaches the investor with a script that reveals nothing, asks whether it agrees to be brought over the wall, and shares details only after it says yes. The investor accepts confidentiality and a trading restriction that lasts until the information is made public or is no longer material, a step often called cleansing. Compliance logs who was crossed, when and on which name.
Analysts meet wall-crossings around confidentially marketed offerings, testing-the-waters meetings before an IPO and overnight block trades, which our explainer on how follow-on offerings and block trades are run walks through. Inside the bank, a banker who wants a research analyst's view on a live deal goes through compliance first.
- Wall-Crossing
The controlled process by which a bank brings an investor or a public-side employee "over the wall" to share material non-public information about a planned transaction. The person agrees to keep the information confidential and not to trade the affected securities until it is made public or is no longer material.
Watch Lists, Restricted Lists and Conflict Clearance
Compliance needs to know which companies the bank holds MNPI on at any moment. It tracks them on two compliance lists, and the main difference between them is who can see them.
The Watch List and the Restricted List
The watch list, often called the grey list, is confidential to compliance. A company goes on it when the bank receives MNPI about it, typically when a mandate begins or a confidentiality agreement is signed, and compliance uses it to monitor trading by the firm and its employees. Circulating it would itself leak the deal.
The restricted list is circulated across the firm. A name usually moves onto it once the bank's role is public, and it can limit proprietary trading, research publication and employee trading in that stock. For an employee, a restricted name is simply not traded in any account you are responsible for.
- Restricted List
A list of companies, circulated within a bank, whose securities the firm and its employees are prohibited from trading or may trade only with limits, usually because the bank is advising on a public transaction involving the company. Unlike the confidential watch list, it is visible firm-wide.
What Happens When a New Deal Opens
Before a bank accepts a mandate, it runs conflict clearance to check whether it already advises a party on the other side or holds a position that creates a problem. Once cleared, a deal moves through a predictable compliance lifecycle:
Conflict check
Compliance confirms the bank can act and that no existing mandate or position conflicts.
Code name and deal team
The deal gets a project name and a named list of people with access to its files.
Watch list
Compliance adds the company, and often the counterparty, to the watch list.
Announcement
When the deal becomes public, the name typically moves to the restricted list.
Removal
After closing or termination, compliance lifts the restriction once nothing material remains non-public.
A deal that dies quietly does not clear itself: the name comes off a list when compliance takes it off, not when the team stops working on it.
Deal confidentiality is learned on the desk, but technical fluency has to come first: Work through accounting, valuation and transaction questions with worked answers, start practicing interview questions for free and arrive at training already speaking the language of live deals.
Personal Trading Rules for Bankers
Personal trading is where compliance reaches into an analyst's private life. Details differ by firm, but the building blocks are consistent because they rest on FINRA rules that apply across the industry, so read your own trading policy line by line.
Disclosing Every Brokerage Account
FINRA Rule 3210 requires people associated with a member firm to obtain the employer's prior written consent before opening an account at another broker-dealer or financial institution where securities can be traded, and to tell that institution in writing who they work for. Accounts opened before joining must be approved within 30 calendar days. Your employer can then receive duplicate statements, and FINRA Rule 3110 requires firms to review employee accounts for trades that may break insider trading rules.
Pre-Clearance and Holding Periods
Bank policies typically require pre-clearance: before each trade, you submit a request through a compliance system that checks the name against the lists and your staffing. Approval is usually valid only briefly, and a cleared trade leaves a record that compliance saw no conflict.
Policies also set minimum holding periods to discourage short-term trading. Credit Suisse's employee trading policy, as filed with the SEC in 2012, set a minimum of generally 30 calendar days for investment banking employees; your firm's figure may differ.
Blackouts on Covered Names
Restricted names are off limits by definition, but sector exposure creates subtler risk. A banker covering an industry holds MNPI about acquirers, targets and competitors at once, and the law does not stop at the company named in the deal. In April 2024 a federal jury found a former biopharma executive liable in SEC v. Panuwat for buying options in a peer company after learning his own employer was about to be acquired, a theory dubbed shadow trading; the court upheld the verdict later that year.
Code Names and Everyday Confidentiality
Most confidentiality is not about lists or systems. It is about daily habits and the small choices that keep a client's name inside the deal team.
Why Every Deal Gets a Code Name
Live deals run under code names, usually "Project" plus a word chosen to say nothing about the company, and the counterparties get names too. Code names keep client names out of email subject lines, file names and calendar invites. They appear in sell-side documents as well: a blind teaser sent to potential buyers describes the business under its project name.
A code name is not a license to be careless. Context gives a company away fast: "Project Falcon, the Boston medical device company with a December signing" is the client's name with extra steps.
Habits That Keep You Clean
Most leaks are not schemes; they are casual conversations and small lapses. The habits that matter are mundane:
- Say nothing about live deals in elevators, trains, restaurants or rideshares.
- Keep deal work on firm devices; never forward files to personal email or discuss deals in personal messaging apps.
- Lock your screen, use a privacy filter when traveling and collect printing immediately.
- Describe your job to family and friends in general terms, never by client.
The family point deserves emphasis, because one of the best-known banker cases of the past decade began with exactly that kind of conversation.
Enforcement Cases Involving Bankers
Cases against bankers fall into a few patterns: family tips, tips between friends and firm-level failures. The outcomes below are stated as courts, the SEC and the press reported them.
Salman: A Citigroup Banker and His Brother
Maher Kara was an investment banker in Citigroup's healthcare group. According to the Supreme Court's opinion, he began discussing his work with his older brother Michael, at first for help with scientific concepts, then shared information about pending deals, sometimes in code words and sometimes about deals he was not working on, to avoid detection. Michael traded and passed tips on, including to Bassam Salman, Maher's brother-in-law, who made over $1.5 million.
Salman was convicted, and in 2016 the Supreme Court unanimously upheld the conviction in Salman v. United States, holding that a gift of inside information to a trading relative or friend satisfies the personal benefit that tipper liability requires. No money has to change hands.
Viggiano: Tips Between Friends
In September 2023 the SEC and federal prosecutors charged Anthony Viggiano, a former analyst at two financial firms reported as Goldman Sachs and Blackstone, with tipping two close friends about upcoming mergers and partnerships; prosecutors said the scheme produced more than $400,000 of illegal profits. Viggiano pleaded guilty and, as Bloomberg reported, was sentenced in July 2024 to 28 months in prison. The SEC's civil case ended in a consent judgment in October 2025, followed by an industry bar.
Morgan Stanley: When the Firm's Wall Fails
In January 2024 the SEC found that from 2018 to 2021 Pawan Passi, head of Morgan Stanley's equity syndicate desk in the Americas, and a subordinate disclosed confidential information about upcoming block trades to buy-side investors, who took short positions ahead of the sales. The SEC also found the firm failed to enforce its information barriers, a violation of Section 15(g) as well as Section 10(b).
Morgan Stanley agreed to pay about $249 million in disgorgement, interest and penalties under the SEC's settled orders, alongside a non-prosecution agreement with federal prosecutors in Manhattan. Passi paid a $250,000 civil penalty and accepted industry bars.
Compliance keeps you employed; technical depth gets you hired: The 160-page PDF covers the accounting, valuation, M&A and LBO questions interviewers ask most, and walk into your first deal team already fluent in the work.
Key Takeaways
- MNPI is information a reasonable investor would find important that has not been broadly disseminated; early deal talks can qualify.
- Banks separate the private side from the public side with information barriers required by Section 15(g).
- Wall-crossing shares deal information on purpose, in exchange for confidentiality and a trading restriction.
- The confidential watch list and the firm-wide restricted list track sensitive names until compliance clears them.
- Personal trading means account disclosure under FINRA Rule 3210, pre-clearance and holding periods, household accounts included.
Conclusion
The rules around MNPI can look like paperwork: forms, lists, pop-up approvals and a code name for everything. Underneath, they protect what a client gives a bank before any fee is paid, which is trust that its plans will stay inside the deal team.
For a new analyst, the practical version is short. Disclose every account before you start, pre-clear every trade, treat every live or possible deal as MNPI, and keep deal talk inside the office. The compliance modules in investment banking analyst training will cover your firm's specifics; take them seriously, because the cases above show how small the first step toward a career-ending mistake can be.
The bankers trusted with the most sensitive mandates are the ones whose discretion nobody ever has to question.


