Introduction
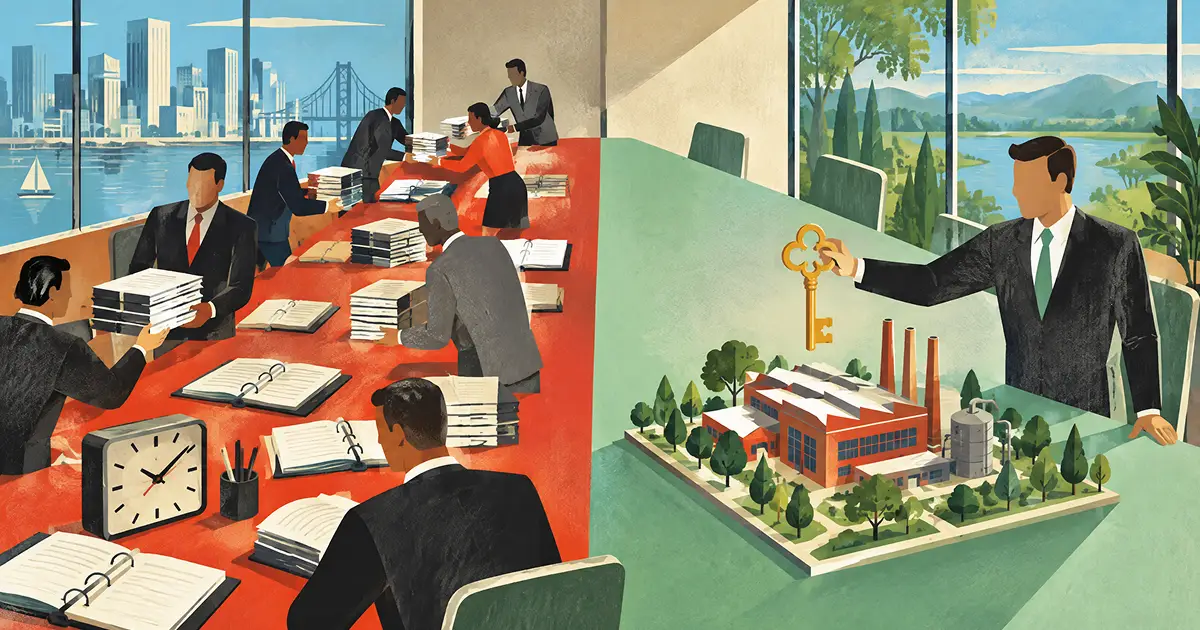
An analyst six months into the job opens a short email from a headhunter: a large buyout fund is interviewing next week for associate seats that start almost two years out. A student holding a banking internship offer and a rare private equity one faces the same fork, just earlier. Both are choosing between advising on a deal and owning its outcome.
That difference drives everything else. A banker is paid to get a transaction signed and closed, and most of the fee lands at closing. A private equity investor decides what to buy and at what price, then lives with the company for years, which is why the richest part of the pay, carried interest, arrives late or never. The models, and often the deals, overlap; deal volume, time horizon and accountability do not.
What follows compares the two careers on work, hours, pay, skills, culture, career path and interviews, then gives an honest way to choose. For the wider industry map behind both, start with how the sell side and buy side split works.
Investment Banking vs Private Equity at a Glance
| Dimension | Investment banking | Private equity |
|---|---|---|
| Side of the deal | Sell side, adviser | Buy side, principal |
| Core work | Pitch, model, run processes | Source, diligence, invest, own |
| Deal volume | Many deals, short involvement | Few deals, multi-year ownership |
| Hours | Spiky, client-driven | Somewhat lower, still intense |
| Pay structure | Salary plus annual bonus | Salary, bonus, carried interest |
| Paid for | Closing transactions | Investment returns |
| Skills built | Speed, polish, process | Judgment, diligence, operations |
| Culture | Large, hierarchical teams | Small, partner-led teams |
| Usual entry | Campus recruiting | Mostly from banking |
| Typical next step | Buy side, corporate, promotion | Promotion, MBA, operating roles |
Read the table as two ends of one transaction rather than a ranking. Banking is the better training ground for breadth and speed; private equity is the seat for ownership and conviction, and it asks for that with fewer, slower, more consequential decisions.
The Work: Advising on a Deal Versus Owning It
What Investment Bankers Actually Do
Bankers sell expertise and execution. Once a bank wins an advisory mandate, usually after weeks of pitching, the junior team runs the machinery of the deal:
- Building the valuation and the operating model
- Drafting the teaser, the confidential information memorandum and management presentations
- Assembling the buyer list and fielding bidders' questions
- Managing the data room and the diligence tracker
- Turning comments from the client, lawyers and senior bankers, often overnight
The defining feature is breadth. An analyst can sit on several pitches and live deals at once, across different clients and sectors, and many of them will never close. That spread is why banking is such an efficient education: an analyst touches far more live transactions in two years than a junior investor will see through to closing.
The economics explain the urgency. Advisory work is paid largely through success fees, so the bank earns most of its money only if the deal completes, and the adviser's job ends at closing.
- Success Fee
The portion of an investment bank's advisory fee that is paid only if the transaction completes, usually calculated as a percentage of deal value. On most M&A mandates it makes up the bulk of the bank's compensation, with smaller retainer or announcement fees along the way. It ties the adviser to getting a deal done, not to how the deal performs afterwards.
What Private Equity Investors Actually Do
A private equity firm raises capital from limited partners, such as pension funds and endowments, buys controlling stakes in companies with that money plus debt, and aims to sell them for more within a few years. A junior investor follows each deal from first look to exit:
Source
Screen teasers sent by bankers and build relationships that surface companies before an auction starts.
Evaluate
Build the LBO model, test the thesis and write a screening memo on whether the deal deserves more time.
Diligence
Coordinate accountants, consultants and lawyers, and pressure-test the business plan with management.
Decide
Line up debt financing, take the deal to the investment committee and submit a binding bid.
Own
Support board work, track the value creation plan and help with add-on acquisitions or refinancings.
Exit
Prepare the company for a sale or IPO, usually by hiring a bank to run the process, which brings the deal back to the sell side.
Most of that effort goes into deals that die. In a survey of 79 private equity investors, Gompers, Kaplan and Mukharlyamov found that for every 100 opportunities considered, the average investor deeply investigated fewer than 24 and closed only about 6. Saying no quickly, with reasons, is a core skill, and portfolio management after closing has no real equivalent in a banker's job.
- Investment Committee
The group of senior partners at a private equity firm that approves or rejects each investment. The deal team presents a memo covering the thesis, valuation, financing, diligence findings, risks and expected returns, and the committee decides whether the firm commits capital. Junior investors draft much of that memo, which is why defending a recommendation matters more in private equity than in banking.
One Deal Seen From Both Seats
Picture a sale process for a mid-sized software company. The banker and the associate are often former analyst classmates, working the same numbers from opposite sides of the table.
| Stage | Banker advising the seller | Private equity associate bidding |
|---|---|---|
| Launch | Drafts teaser and CIM, builds buyer list | Screens teaser, signs NDA |
| First round | Answers questions, collects indications | Builds LBO, writes screening memo |
| Diligence | Runs data room and management meetings | Commissions diligence, tests the thesis |
| Final bids | Compares offers, negotiates terms | Secures financing, goes to committee |
| Closing | Collects the success fee | Starts owning the company |
| Next five years | Moves on to new mandates | Board work, value creation, exit planning |
A real deal shows the asymmetry. Hilton's 2007 merger proxy disclosed that UBS, its lead financial adviser, would be paid $33.6 million, of which $31.6 million depended on completion; the deal closed in October 2007 and the adviser's stake in the result ended there. Blackstone had barely started: it marked the equity down by about 70% during the financial crisis before the Hilton buyout became a gain of roughly $14 billion by the final share sale in 2018.
Hours and Lifestyle
Banking: Deadline-Driven and Spiky
Banking hours follow the deal calendar: a bid deadline, a board meeting, a signing date, a client who wants the book by morning. Long weeks became enough of a problem that the largest banks have moved to limit them. JPMorgan confirmed in 2024 that it would hold junior bankers to 80 hours a week in most cases, with live deals exempt, as Fortune reported, while Bank of America began requiring daily logs of hours and deals.
The exemption says a lot. A cap that steps aside for live deals tells you the peaks are the job. Quiet weeks happen, but an analyst rarely controls when a busy one ends, because staffing decisions and client deadlines sit above them.
Private Equity: Fewer Hours, Different Pressure
Private equity weeks are usually shorter, not light. Compensation data from search firm Odyssey, as reported by eFinancialCareers, put average working weeks at about 70 hours at upper-middle-market firms and about 60 once smaller firms are included, with longer hours not unusual at the biggest funds. During diligence and the run-up to signing, an associate's week can look exactly like banking.
The pressure also changes shape. There is less reactive work for clients and more self-generated work: one more data cut, one more expert call, one more revision before committee. And the work does not stop at closing, because portfolio companies produce board meetings, quarterly reviews, refinancings and add-on deals of their own.
Pay: Salary, Bonus and Carried Interest
Investment Banking Pay: Cash on a Predictable Ladder
Banking pay is salary plus an annual bonus, with the bonus set by performance buckets within each class. Our banking salary and bonus guide puts first-year analyst total pay at large New York banks at roughly $180,000 to $220,000, rising to roughly $275,000 to $375,000 for a first-year associate. The structure is transparent and mostly cash at junior levels, and it is paid each year whether or not a client's deal later works out; deferred stock starts to appear in bonuses from the associate level up.
Private Equity Pay: Similar Cash, Different Upside
At the junior level the cash gap is smaller than its reputation. Heidrick & Struggles' 2025 North America private equity compensation survey put upper-quartile cash pay (2024 base plus bonus) for associates and senior associates at about $200,000 at firms managing under $500 million, rising to about $400,000 at firms managing $40 billion or more. About three-quarters of respondents said their bonus plans were discretionary rather than formula-based.
| Seat | Reported cash pay | Source | Long-term upside |
|---|---|---|---|
| First-year banking analyst | $180K to $220K | Salary guide range | Promotion |
| First-year banking associate | $275K to $375K | Salary guide range | Promotion, larger bonus pool |
| PE associate, firm AUM under $500M | About $200K | Heidrick, upper quartile | Little or no carry |
| PE associate, firm AUM of $40B and above | About $400K | Heidrick, upper quartile | Carry that grows with seniority |
The real difference sits beyond the cash. A banker's upside is promotion up a well-mapped ladder. An investor's is a share of the fund's profits, which starts small, vests slowly and pays late.
How Carried Interest Works for a Junior Investor
- Carried Interest
The share of a private equity fund's profits, typically 20%, that goes to the fund's general partner, and through it to the firm's investment professionals, rather than to the fund's investors. It is usually paid only after investors have received their capital back plus a preferred return, often 8% a year, and individual allocations vest over several years. Carry is the main reason senior private equity pay can far exceed banking pay.
The firm divides that 20% among its people as shares of the carry pool, often quoted in points, where one point is 1% of the pool. A rough value of an allocation, the way compensation surveys estimate it, looks like this:
Take a $2 billion fund that returns its investors' money twice over, a $2 billion profit. The carry pool is $400 million, and a senior associate or vice president holding 0.25% of it has about $1 million of carry on paper. Many associates hold no carry at all, and even a real allocation is worth that much only on paper, for four reasons:
- Vesting: allocations vest over years; in Heidrick's 2025 survey five years was the most common time to vest fully, and 46% of respondents said vesting runs from the start of each new fund.
- The waterfall: investors usually get their capital and preferred return before carry is paid, a sequence covered in detail in our guide to the carried interest waterfall.
- Exit timing: a fund typically invests over roughly its first five years and sells over the years after, so most carry is paid in the back half of its life.
- Leaving: depart before vesting and the unvested carry is usually forfeited.
Skills, Culture and Team Size
What Each Seat Teaches
Banking builds execution skills that transfer almost anywhere. Private equity builds investment judgment, which is harder to learn and harder to prove on a resume. The model is common ground; what each seat rewards around it is not:
- Banking rewards: modeling speed and accuracy, presentation polish, running a process with many parties, client service, and breadth across sectors and deal types.
- Private equity rewards: forming a view and defending it, depth of diligence, understanding how a business really makes money, structuring debt, and working with management after closing.
A banker's best work is a flawless book delivered on time. An investor's best work is often a well-argued no, and junior associates are judged partly on whether the deals they push forward deserve the firm's attention.
Large Banks, Small Investment Teams
Banks run on scale: big analyst classes, staffing pools, formal training programs and a layered hierarchy from analyst to managing director. Private equity firms are small by comparison; Heidrick & Struggles' survey describes hiring firms as looking for people who can grow what is usually a small operation. A deal team is often a handful of people, from associate to partner.
That size changes the daily experience in three ways:
- Access: associates sit closer to partners and hear the real debate at committee.
- Accountability: there is nowhere to hide on a four-person team, and many firms run the associate role as up or out.
- Apprenticeship: training comes from the people around you rather than a structured program, so the quality of your deal team matters more than the firm's brand.
Fund size shapes the job as much as the label does. A middle-market associate is more likely to help source deals and work closely with management, while a megafund associate spends more of the week on modeling, diligence and financing for much larger transactions.
Career Paths Between the Two
The Classic Route: Banking First
The well-worn path runs from a summer internship to a two-year banking analyst stint to a pre-MBA associate seat at a fund. Large funds hire much of each class through on-cycle recruiting, a sprint that has crept earlier over the past decade and now reaches analysts within months of their start date.
- On-Cycle Recruiting
The compressed, headhunter-coordinated process in which large private equity firms interview investment banking analysts for associate roles that start roughly 18 to 24 months later. Interviews, modeling tests and offers can all happen within days. Firms that do not fill their class this way, along with many middle-market funds, hire off-cycle on a rolling basis.
The timing has become a flashpoint. JPMorgan told incoming analysts in June 2025 that accepting a future-dated job within their first 18 months would end their employment, as Fortune reported. Even so, eFinancialCareers reported that Blackstone, Carlyle, TPG and others were interviewing in early January 2026 for associate seats starting in late 2027, with one analyst accepting an offer the same day his interviews began. For how to plan the move from inside a bank, see the banking-to-private-equity timeline.
Going Straight Into Private Equity From College
It is possible, but the door is narrow. Some of the largest firms, Blackstone and KKR among them, recruit undergraduate summer analysts into their private equity businesses and make full-time analyst offers to strong interns. The scale is tiny: Fortune reported in 2023 that Blackstone received 62,000 applicants for 169 first-year analyst positions across the whole firm.
- Upside: you learn investing from day one and skip a recruiting cycle.
- Downside: fewer seats, less deal breadth, and training that depends heavily on your team.
- Fallback: if investing turns out to be the wrong fit, your next move looks more like other buy-side or corporate roles than a reset into banking.
Pre-MBA, Post-MBA and the Long Climb
The pre-MBA associate role has traditionally lasted two to three years. At the end, associates are promoted to senior associate, move to another fund, or leave for business school; more firms now promote strong associates without an MBA, though practice varies widely. Post-MBA seats exist, but they are fewer, and large funds tend to fill them with people who invested before business school.
Banking has its own ladder: analyst to associate in about three years (JPMorgan cut its track to two and a half in 2025), then vice president, director and managing director over a decade or more. Staying in banking is a career, not a failure to exit.
Where Each Path Leads Next
Both seats open doors, but not the same ones. Two years of banking remains the broadest launch pad in finance, while a few years in private equity points you more narrowly toward investing and operating roles:
- From banking: private equity, growth equity, hedge funds, private credit, corporate development, or promotion to associate.
- From private equity: promotion toward vice president, a move to another fund, business school, or a strategy or finance role at a portfolio company, and later in a career, raising a fund of your own.
How the Interviews Differ
Both processes test technicals and fit, but private equity adds a question banking interviews rarely ask: would you put money into this company? The investment judgment test sits on top of the technical one.
| Element | Investment banking interview | Private equity interview |
|---|---|---|
| Technicals | Accounting, valuation, M&A | LBO mechanics, returns, structure |
| Modeling | Rare at entry level | Timed LBO test or take-home case |
| Mental math | Occasional | Paper LBO in a few minutes |
| Deal discussion | Deals you followed | Your own deals, as an investor |
| Core question | Can you execute? | Should we invest? |
For students, the banking interview is the gate that matters first. For analysts, the private equity case study asks for a recommendation, invest or pass, defended with returns, risks and mitigants, and the fastest warm-up is a paper LBO you can finish in your head.
LBO and valuation questions decide banking and buy-side interviews alike: Work through LBO, valuation and deal questions with worked answers, start practicing interview questions for free and walk into either process knowing exactly where your gaps are.
How to Choose Between Them
Who Thrives in Investment Banking
Banking suits people who like momentum and a finished product. You will probably enjoy it if you:
- get energy from several projects and deadlines at once
- like learning a new company or sector every few weeks
- prefer cash pay that does not depend on an investment's result
- want the widest set of options two years from now
Who Thrives in Private Equity
Private equity suits people who want depth over breadth and can live with slow feedback. It fits you if you:
- would rather know five companies deeply than fifty briefly
- are comfortable defending an opinion to partners who will poke holes in it
- can wait years to learn whether you were right
- accept that the biggest part of the pay is deferred and uncertain
If You Cannot Decide Yet
For most students the honest answer is to start in banking. It is the main feeder into private equity, while far fewer people move from a fund back into banking, so it keeps both doors open at the cost of two demanding years. Then test the investing question instead of guessing.
Your answer to that last question is one of the best signals you have. People who love the process tend to be happiest advising; people who keep asking whether the deal is any good tend to end up investing.
Banking or buyout, the technical bar comes first: Our 160-page PDF covers the accounting, valuation and LBO questions both interviews test, and prepare for whichever door you choose.
Key Takeaways
- The core difference is advising versus owning: bankers are paid when deals close, investors on how investments perform.
- Banking offers breadth, many deals and structured training; private equity offers depth, fewer deals and multi-year ownership.
- Private equity hours are usually lower on average, but diligence peaks and accountability keep the pressure high.
- Junior cash pay is broadly comparable; carried interest is the long-term difference, and for juniors it vests slowly and pays late.
- The classic path is banking first, then a pre-MBA associate seat; direct-from-college private equity seats exist but are very scarce.
- Private equity interviews add investment judgment to the technicals: paper LBOs, modeling tests and invest-or-pass cases.
Conclusion
Investment banking and private equity sit on the same deals, so it is easy to mistake them for one career at two pay grades. They are different jobs. The banker's skill is getting a transaction done well and on time, across many clients; the investor's skill is deciding which transaction deserves to happen at all, then carrying the consequences for years.
That difference shows up everywhere: in how many deals you touch, in what your hours feel like, in when you get paid, and in what a good day looks like. It also explains why carried interest is both the great prize of private equity and a poor reason to choose it at 22.
If you are unsure, banking first is the choice that preserves the most options, and the years in it will tell you whether you love the process or the bet. Pick the seat whose daily work you would still choose if the pay were equal, because at the junior level, it nearly is.


